
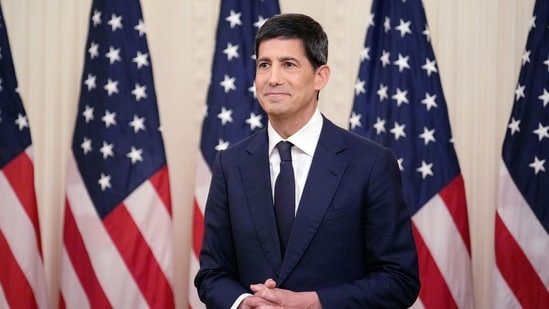
Former Fed governor Kevin Warsh, who built a reputation for hawkish views on inflation, monetary policy and the Fed’s role in the economy, is back in the central bank spotlight.

Warsh’s economic philosophy is now expected to guide his new term as Fed chairman, based on his recent testimony and long-term stance.
Here are five key things to know about him.
1. Age, nationality and background
Kevin Warsh is an American economist who served as a governor of the Federal Reserve until 2011. While detailed personal measurements such as height are not included in the official disclosure, public records confirm he is a U.S. national with a long career in government, academia and finance.
Since leaving the Fed, he has been a prominent economic voice, frequently commenting on monetary policy and inflation.
2. Parents and early life
Wash comes from a professional family background, but his personal life has generally not received much attention. Public biographies chronicle his upbringing in the United States and education at elite institutions, experiences that later influenced his entry into economic policy and government service.
3. Net worth and financial condition
Warsh’s finances are closely tied to his post-Federal career in finance and consulting roles. His net worth is estimated to be substantial, driven by investments and private sector roles, according to financial disclosures and reports cited by outlets including Reuters and Forbes, but the exact figure varies by estimate.
4. Inflation: “an alternative” and the central focus of his philosophy
Warsh took a decidedly aggressive stance on inflation control. In written testimony cited by Reuters, he said:
“Inflation is a choice and the Fed must take responsibility for it.”
He also believes that inflation is driven by excessive money creation and government spending, saying:
“I think you get inflation when governments print too much money … central banks and, broadly speaking, governments spend too much.”
His stance suggests the Fed will take a more accountability-driven approach compared to recent policy frameworks.
5. Doubts about Fed communications and data reliance
Warsh also challenged the modern Fed’s approach, particularly its forward guidance.
“I don’t believe in forward guidance,” he told lawmakers, arguing the Fed should not preview future decisions. He also questioned the accuracy of economic forecasts, saying policymakers should focus “on the left of the decimal point, not the right.”
That reflects his broader belief that the Fed should act more decisively and rely less on specific economic data and forecasts.


